
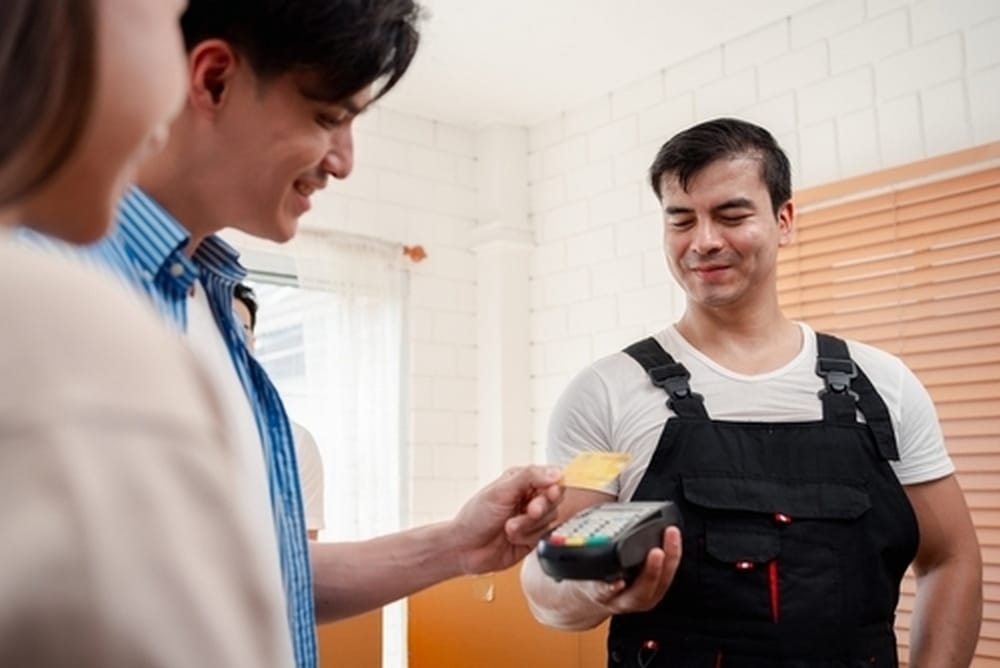
Getting paid used to mean invoicing, waiting, and chasing. Payment processing services make it possible to get paid the moment a job is done, whether that’s a card tap on the doorstep or an online invoice paid on a phone. Here’s how it works, what it costs, and how to choose the setup that fits your business.
| Quick Answer: To take card payments as a tradesperson, you need a payment processor (or an all-in-one field service platform with one built in), a way to capture card details on-site or online, such as a mobile card reader or a payment link, and a merchant account to receive the funds. Most processors charge 1.5% to 3.5% per transaction, and setup can take as little as a day with an integrated platform like Service Fusion Payments. |
What Is Payment Processing, and How Does It Work?
Payment processing is the act of digitally transferring money from one party to another. For a home service or trade business, that’s usually a payment from a customer.
A payment typically moves through three stages: authorization (the customer’s bank confirms the funds are available), verification (fraud and security checks run in the background), and settlement (the money actually lands in your account).
Multiple systems can carry that payment:
- Debit and credit cards
- ACH (Automated Clearing House) transfers, also called bank-to-bank transfers
- Digital wallets, such as Apple Pay or Google Pay
- Mobile payments, taken on-site with a card reader.
Related Reading: The Future of Online Payments: What You Need to Know
A single payment involves more parties than most customers realize: the customer’s bank authorizes the charge, a payment gateway passes the encrypted data along, a payment processor handles the technical transfer, and your merchant account (or acquiring bank) receives the funds. Security standards like PCI DSS run in the background throughout, and the whole thing usually takes seconds.
Related Reading: How Payment Processing Works for Contractors walks through this process step by step, specifically for contractors and field service businesses.
What’s the Difference Between a Standalone Payment Processor and an Integrated Software Suite?
A standalone online payment-processing service handles only transactions. It’s a fast way to start accepting cards, but the payment data lives separately from your job and invoice records.
An integrated field service management platform with built-in payment processing keeps everything in one place. A technician can convert a completed job to an invoice and collect payment on the spot, without re-entering anything into a separate system. The payment record automatically appears next to the job history.
What Are ACH Payments?
ACH stands for Automated Clearing House, the network that moves money directly between US bank accounts electronically, without a card or card network involved. Payments are processed in batches rather than in real time, which is why ACH transfers take longer to settle than a card swipe.
Most ACH transfers settle in one to three business days. Same-day ACH is available from many processors for an extra fee, usually capped at $25,000 per transfer. An ACH payment can still fail after it’s submitted, most often because the customer’s account has insufficient funds, the account has been closed, or the account details don’t match the bank’s records.
ACH is commonly used for recurring payments, such as maintenance contracts, and for larger one-off invoices where a card’s percentage fee would take a meaningful bite out of the payment.
ACH vs. Card: The Cost and Speed Trade-Off
Once you know what each option entails, the choice usually comes down to two things: what it costs you and how quickly you need the money.
| ACH/Bank Transfer | Credit or Debit Card | |
| Typical cost | A flat fee (0.25–0.75) or 0.5%–1% of the transaction | 1.5%–3.5% of the transaction |
| Typical settlement time | 1–3 business days | Varies by processor, often faster for card-present transactions. |
| Best suited to | Large invoices, where a percentage fee would eat into margin | Smaller jobs, or when the customer wants to pay on the spot |
| Failure risk | Can bounce for insufficient funds or a closed account | Declines instantly at the point of sale. |
The gap adds up on bigger jobs. On a $5,000 installation, a 2.9% card fee costs $145. The same payment via ACH at a 0.5% rate costs $25. For recurring maintenance contracts or smaller call-outs, the convenience of a card usually outweighs the difference.
Want to stop choosing between speed and cost on every invoice? Service Fusion Payments lets you accept cards, ACH transfers, and digital wallets from the same platform you already use to manage jobs and invoices. See how it works.
Payment Gateway vs. Payment Processor vs. Merchant Account
These three terms get used interchangeably, but each does a different job:
- A payment gateway is the front-end tool that captures and encrypts the customer’s payment details at checkout.
- A payment processor is the back-end technology that authorizes the transaction and handles the technical transfer between banks.
- A merchant account is the holding account that receives funds once the processor has cleared them, before they reach your business bank account.
Some providers bundle all three into one product; others require you to set each up separately. Either way, understanding the split helps you ask the right questions when you’re comparing payment processing services.
What Is a Payment Processing Fee?
A payment processing fee is the cost your business pays to accept a digital payment. For card payments, that fee usually includes the card network’s interchange fee, the processor’s markup, and sometimes additional assessment or platform fees. For ACH payments, the fee is usually lower because the payment moves from bank to bank rather than through a card network.
The important thing is to compare the full cost, not just the headline rate. A processor might advertise a low percentage but still charge monthly fees, chargeback fees, hardware fees, statement fees, or higher rates for online transactions.
Which Payment Processing Pricing Structure Is Right for You?
Card processing fees typically run 1.5% to 3.5% of the transaction, but how that fee is charged depends on the pricing structure your processor uses.
| Type | How It Works | Pros | Cons |
| Interchange-plus | You pay the card network’s interchange rate plus a markup (percentage, flat amount, or both). | Often the cheapest overall, especially at high volume. | The rate changes per transaction, which can complicate budgeting. |
| Flat rate | You pay a single rate on every transaction. | Predictable and simple to budget for. | Usually costs more overall than interchange-plus. |
| Tiered | Transactions are sorted into pricing tiers with different rates. | A middle ground between the other two. | Costs more than interchange-plus, though usually less than flat-rate at volume. |
Check Service Fusion’s pricing packages to see how payment processing fits alongside the rest of your software costs.
Ensuring Customer Security When Accepting Payments
In 2024, 79% of organizations experienced attempted or actual payment fraud, according to the 2025 AFP Payments Fraud and Control Survey. A payment processor with strong security standards reduces that exposure, and a security breach on your end can cost you the customer’s trust and their business.
Look for these security elements when choosing a payment processor:
- Encryption to protect data in transit
- Regular software and hardware updates
- EMV (chip) compatibility to limit card-present fraud
- CVV checks to prevent fraud and chargebacks
- Clear refund and chargeback policies.
How to Choose the Right Payment Processing Setup
The right setup depends on how your customers typically pay, the average invoice size, and how much manual admin you want to eliminate.
Choose card payments if most jobs are paid on-site and customers expect to pay immediately by card or digital wallet. Choose ACH for larger invoices, recurring, or tied to maintenance agreements where lower fees matter more than instant settlement. Choose an integrated payment setup if you want payments, invoices, job records, and customer history connected instead of spread across separate systems.
For most trade businesses, the best setup is the one that helps you collect payment quickly, reduce manual reconciliation, and give customers a simple way to pay.
Payment Processing Features Service Businesses Should Look For
A good payment setup for a trade business should support how work is actually done in the field. Look for:
- Multiple payment options, including cards, ACH, and digital wallets
- Mobile payment collection, so that technicians can take payment at the job site
- Online payment links or forms for invoice follow-up
- Clear processing fees and settlement timelines
- Security features such as encryption, EMV support, and CVV checks
- Integration with invoices, job records, and accounting software.
The easier the payment process is for both the technician and the customer, the less time your office spends chasing, matching, and correcting payments later.
Getting Paid Faster with Service Fusion Payments
Chasing down late payments and manually matching bank statements to invoices is one of the biggest time sinks when running a service business. Service Fusion Payments is built into the Service Fusion workflow specifically to remove that step. It covers the situations that come up most on the job:
- Mobile payments in the field, using the Service Fusion Payments app and a Stripe card reader
- Online payment forms that accept cards, debit, or bank-to-bank transfers, with automated follow-ups for unpaid invoices
- Card-on-file, so repeat customers don’t have to re-enter payment details
- ACH check capture, which scans and processes checks digitally
- Job deposits collected upfront, so scheduled work isn’t canceled or deferred at the last minute.
Pricing is exclusive to Service Fusion customers, with credit card processing rates starting at 2.90% + $0.30 per transaction. Because payment data is in the same system as your job and invoice records, monthly reconciliation is a matter of checking one dashboard rather than matching numbers across two systems.
A Few Final Considerations
Keep these things in mind when exploring payment processors for your home services company:
- You may need to request a quote rather than finding pricing listed on the processor’s website.
- Online transactions tend to cost more than card-present transactions, reflecting the higher fraud risk.
- Some processors require you to use their merchant account; others let you bring your own, which is usually the more economical option.
- Switching processors partway through a contract can trigger a cancellation fee, so check the contract terms before signing.
- If customer financing is relevant to your business, some large-ticket jobs are better suited to a financing option than a standard payment processor.
How Online Payment Processing Benefits Home Service Providers
Cash and checks are no longer the default, and offering a digital option benefits your business as much as it benefits your customers:
- It gets you paid faster. A completed transaction can take seconds rather than weeks.
- It reduces fraud risk when handled by a processor that meets proper security standards.
- It makes reconciliation easier when payment data connects directly to your job and invoice records.
Broader consumer payment expectations are shifting toward speed, security, and choice. Onbe and NRG’s 2026 Payouts Landscape report found that 80% of consumers say the ability to choose their preferred payment method is important, and 89% prefer digital payment methods when receiving a payout. For service businesses, the takeaway is simple: customers increasingly expect payment experiences to be fast, flexible, and digital.
Related Reading: How Online Payment Platforms Can Benefit and Grow Your Home Service Business
FAQs: Payment Processing for Service Businesses
A few questions often come up once businesses start comparing payment processing services.
What’s the difference between a merchant account and a payment gateway?
A payment gateway captures and encrypts payment data at the point of sale. A merchant account is the back-end holding account that actually receives the funds once they’ve moved through the gateway and processor.
What’s the difference between flat-rate, tiered, and interchange-plus pricing?
Flat-rate charges one rate on every transaction. Tiered pricing sorts transactions into a small number of pricing bands. Interchange-plus charges the card network’s actual rate plus a fixed markup, which is usually the cheapest option at higher transaction volumes, but the least predictable month-to-month.
Is ACH cheaper than credit card processing?
Usually, yes. ACH transfers typically incur a flat fee of $0.25 to $0.75, or 0.5% to 1% of the transaction, compared with 1.5% to 3.5% for card payments. The trade-off is speed: ACH settles in one to three business days, while card payments are typically faster.
How long does it take to get paid after a customer pays online?
It depends on the payment method and processor. Card payments often settle faster than ACH transfers, which typically take one to three business days. Check your specific processor’s payout schedule, since this varies.
Can I charge customers a fee for paying by credit card?
Rules on card surcharging vary by state, and a small number of states restrict or prohibit it. Check your state’s current rules, and those of the card networks you accept, before adding a surcharge.
What’s the average credit card processing fee?
Most businesses pay between 1.5% and 3.5% per transaction, depending on the card type, pricing structure, and processor.
Is flat-rate or interchange-plus pricing better?
Flat-rate pricing is simpler and easier to budget for. Interchange-plus pricing is often cheaper at higher transaction volumes, but the rate varies by card type and transaction. The better choice depends on your invoice size, monthly volume, and the level of predictability you want.
Ready to Simplify Payment Processing?
Service Fusion Payments is built into the same platform you use to schedule jobs, send invoices, and track technicians, so payments are one less system to manage. Get a free demo to see it in action.
Article Sources
Onbe/NRG. 2026 Payouts Landscape Report. Accessed August 14th, 2026.
NerdWallet. Credit Card Processing Fees: What Small Businesses Should Know in 2026. March 6th, 2026
Square. What Are ACH Payments and How Do ACH Transactions Work? February 28th, 2026
Association for Financial Professionals/Truist. Survey: 79% of Organizations Were Victims of Attempted or Actual Payment Fraud Activity in 2024. April 15th, 2025
Related Posts
FieldPulse vs Housecall Pro: Full Comparison
Continue ReadingPlumbing License Requirements by State
Continue ReadingStay Informed
Get the latest news and insights plus, Service Fusion offers and updates.Thank you for your submission.
SHARE